Bond market is starting to get interesting, which is rarely a good thing.
10 year treasury yield hit 4.8% yesterday, was 4% in March. Shape of the graph is not a sign of happy things to come:
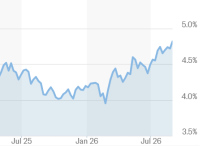
Even the 2 year is going up, was 3.3% in March, now 4.4%, despite Beasant increasing the buyback of government debt to reduce interest rates on US debt. It worked briefly but as you can see from the chart and headlines in the news, it didn't work.
Unfortunately, the bond market is also unimpressed by the UK's debt position too, which is why 10 year gilts have gone from 4.2% to 5.2% since March and rising rapidly over the past few days.
5% isn't disaster territory (although with GDP growth at 1% levels, it's a big problem), but if the UK and US start hitting 6% and higher (and the 30 year gilt is almost at 6%), then it really could start to get quite sticky.
France and Italy are also seeing higher rates, both have massive government debt to GDP, Ireland is in a very good position now, but there could end up being a bit of problem, the French are trying to reduce the deficit below 5%, while at the same time, debt to GDP is almost 115% and GDP growth is almost nonexistent.
Overall debt to GDP in the Eurozone is 87.8%, and 10 year euro area bonds are only 3.7%, so it'd be a political rather than real financial crisis for the Eurozone overall should France's position get really difficult.
I think with bond markets skittish, if we have AI companies getting into trouble, I really think it could go bad really quickly in the US, with major contagion problems for the rest of the world due to the sheer volume of US treasury bonds held by other governments.
As for the AI companies, that is a bomb waiting to explode. Lots of off balance sheet shenanigans, disguised vendor financing, circular deals and insane assumptions about future revenue growth.
OpenAI are targeting $280 billion in revenue in 2030, off the back of over $600bn in spending between now and then. Their revenue last year was $13 billion.
For context, Microsoft's entire revenue for 2026 fiscal year was $331bn, up from $280bn in 2025.
Anthropic are expecting to hit $200bn by 2028*.
SpaceX are looking to hit $1 trillion in revenue by 2030 (Wall Street estimates a mere $300-$400 billion). 2026 revenue is projected to be $45bn for 2026.
Microsoft themselves are aiming for $500bn by 2030, Amazon's AWS $300bn (from $169bn), Oracle $225bn (from $67bn), Google $900bn (from $500bn) and so on (e.g. Coreweave $60bn from $12bn).
Barclays estimate that Anthropic and OpenAI make up 73% of all of Amazon's AI revenues. Amazon are planning on spending over $220bn in build out this year. Which is a lot.
Those two are estimated to make up well over half of all Google Cloud AI revenues, 74% of Microsoft
That's a lot of upgraded Copilot licenses and Claude Code subscriptions, especially when you bring in depreciation, cost of capital, positive operating margins and competition.
The latter point is the one that makes me skeptical that OpenAI and Anthropic are ever going to really realise the promise.
Thing about it is if you're operating a production system that's actually doing something in the real world, you really should avoid being dependent on the latest model. If I've got an automated agent that is doing a task for me, I do not want that automatically updated and the fecking thing suddenly doesn't work properly for reasons that are entirely unclear to me.
R&D? Sure, use the latest model. But for volume production where it's doing something useful, probably best to stay a little behind the curve.
Which is exactly where the open source models are. And if they break, I can do something about it. And Trump can't turn them off because he's had another hissy fit.
In any case, it's not reliable enough in production today to do much beyond customer service chatbots that everyone hates, processing flows of log and monitoring data for events and better predicting customer preferences. Useful, sure, but there's already pretty clever data analysis software in those areas so it's not like you're replacing a horse with a car.
I'm very much a believer in AI (with major caveats), but right now, just don't see where the source of money into the AI industry is going to come from to justify the valuations. Here are some more statistics to put the revenue figures above in context:
Worldwide: The Software market is expected to witness a remarkable growth trajectory worldwide. Definition: In general, software is defined as a set of instructions written as programming code to execute specific tasks on a computing device.

www.statista.com
"The Software market is expected to witness a remarkable growth trajectory worldwide.
It is projected that by the year 2026, the revenue in this market segment will reach an impressive figure of US$779.07bn.
Within this market, Enterprise Software is anticipated to dominate with a projected market volume of US$334.01bn by 2026."
That's the entire global software market.
Know it seems like a long ramble from bond yields to AI revenue projects, but I believe the two are very, very heavily linked and if one goes, the other will too. The US economy is incredibly exposed to AI investment, an estimated half of all GDP growth in the US is tied to AI, the stock market is being very, very heavily driven by AI and if things fall apart financially, it'll have a wide range of knock on effects on all sorts of industries and countries.
*the numbers cited are a bit weird for Anthropic's projections for 2026, they're very much into Annualised Run Rate as a measure, and boasting it hit $65bn. This is a bit cheeky, as there's already a use for ARR, Annualised Recurring Revenue. Was a huge thing at a former employer, it's about the multi-year fixed commitments you have signed with customers. But for an API driven company like Anthropic, that's not their main financial model, you can switch your API pretty quickly to a totally different provider, within seconds if you have a good enough system around your AI.


 www.theguardian.com